Back
How a debt consolidation loan helped Kim and Bob combine $37k of debt
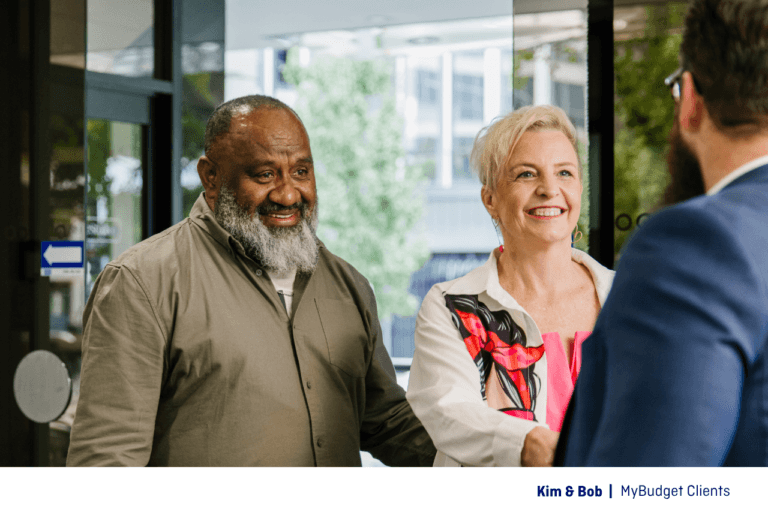
When you’re juggling several debts, it can be hard to see how you’ll ever get on top of them.
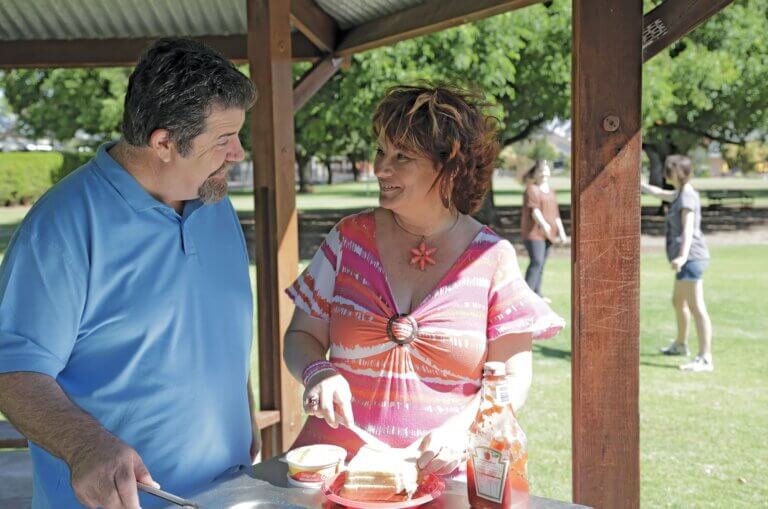
Kim and Bob know what it feels like when debt starts piling up.
They first came to MyBudget 16 years ago with around $28,000 owing across 12 different accounts. There were credit cards, overdue household bills, rental arrears and other debts, all competing for money at the same time. Within 13 months, they had paid it off.
Years later, their needs had changed. With new loans and credit balances to manage, they wanted to find a way to make their repayments more manageable.. Their circumstances were different this time, and so was the solution.
In April 2024, MyBudget Loans helped Kim and Bob to consolidate five debts totalling $37,222.07 into one debt consolidation loan. The change simplified their repayments and freed up $875 a month in their budget, or around $10,500 a year.
It’s really taken that burden off us as parents.
Kim | MyBudget Client
Five debts, one manageable repayment
By 2024, Kim and Bob were carrying two personal loans, a store card, a credit card and a ZipPay balance.
Together, they added up to $37,222.07.
| Debt | Balance |
|---|---|
| Bob’s MoneyPlace personal loan | $7,255.48 |
| Kim’s MoneyPlace personal loan | $17,801.35 |
| Kim’s GEM Visa store card | $5,671.66 |
| Bob’s Bankwest credit card | $4,999.86 |
| Bob’s ZipPay balance | $1,493.72 |
| Total | $37,222.07 |
That meant five balances to keep track of and five repayments competing with the rest of the family’s everyday bills and living costs.
Debt consolidation gave Kim and Bob another option. MyBudget Loans helped them combine the five debts into a single loan, leaving them with one repayment to manage.
The difference to their monthly budget was $875.
That was another $875 available each month for the rest of their expenses, savings and plans and $875 worth of breathing room.
How did debt consolidation work for Kim and Bob?
A debt consolidation loan combines several existing debts into one new loan. Instead of paying different lenders separately, you make one repayment towards the consolidated balance.
For Kim and Bob, the process started with their existing budget.
MyBudget Loans looked at what they could afford, then worked through available lending options with them. Their budget was checked before they borrowed so the new repayment could fit alongside their existing household expenses.
Kim describes the process as straightforward: they discussed what they needed, looked at the available options and chose the one that suited them.
That connection between the loan and their household budget was ideal for a couple who had already spent years learning how much easier money could feel when they knew what was coming up.
Bob remembers that feeling from the first time they got their finances under control:
When we rang MyBudget and they did that for us, it’s like you start to breathe good air.
Bob | MyBudget Client
Their first debt payoff had started 14 years earlier
Originally from New Zealand and Vanuatu, Kim and Bob built their life in Australia with their four children. And their history with debt goes back much further than their 2024 consolidation.
When they joined MyBudget in 2010, they had four young children and around $28,000 owing across 12 accounts. Bob had also been diagnosed with cancer and couldn’t work as much while receiving treatment.
Bills fell behind. Credit cards became harder to catch up on. Debt collectors were calling, their power was close to being disconnected and the family was facing the possibility of losing their home.
Kim remembers how desperate things had become.
At the time, consolidation wasn’t available to them. They had already tried to get consolidation loans elsewhere and had been turned down.
Instead, MyBudget helped them organise their income and repayments around what they already had. 13 months later, the $28,000 was gone.
That was mind blowing. We did not think that would ever happen.
Kim | MyBudget Client
That experience stayed with them. Over the years that followed, their finances changed, their family grew older and life threw more at them, including Kim’s own cancer diagnosis in 2019.
By 2024, they weren’t the same couple who had arrived at MyBudget overwhelmed by 12 different debts. They had years of budgeting behind them and a much clearer idea of what they could afford.
This time, consolidating their debts was an option.
Was the debt consolidation loan worth it for them?
For Kim and Bob, the most immediate change was simple: five debts became one loan, and their monthly budget had an extra $875 available.
That worked out to around $10,500 over 12 months.
A lower monthly repayment is only one part of deciding whether a debt consolidation loan is right for you. You also need to look at the interest rate, fees, loan term and total amount you’ll repay.
Stretching a loan over a longer period, for example, may reduce the monthly repayment but increase how much you pay overall. That’s why the new loan needs to be looked at alongside your budget rather than judged on the repayment alone.
Kim and Bob could see how the consolidation fitted into theirs.
It gave them one repayment instead of five and more room each month for the rest of their plans.
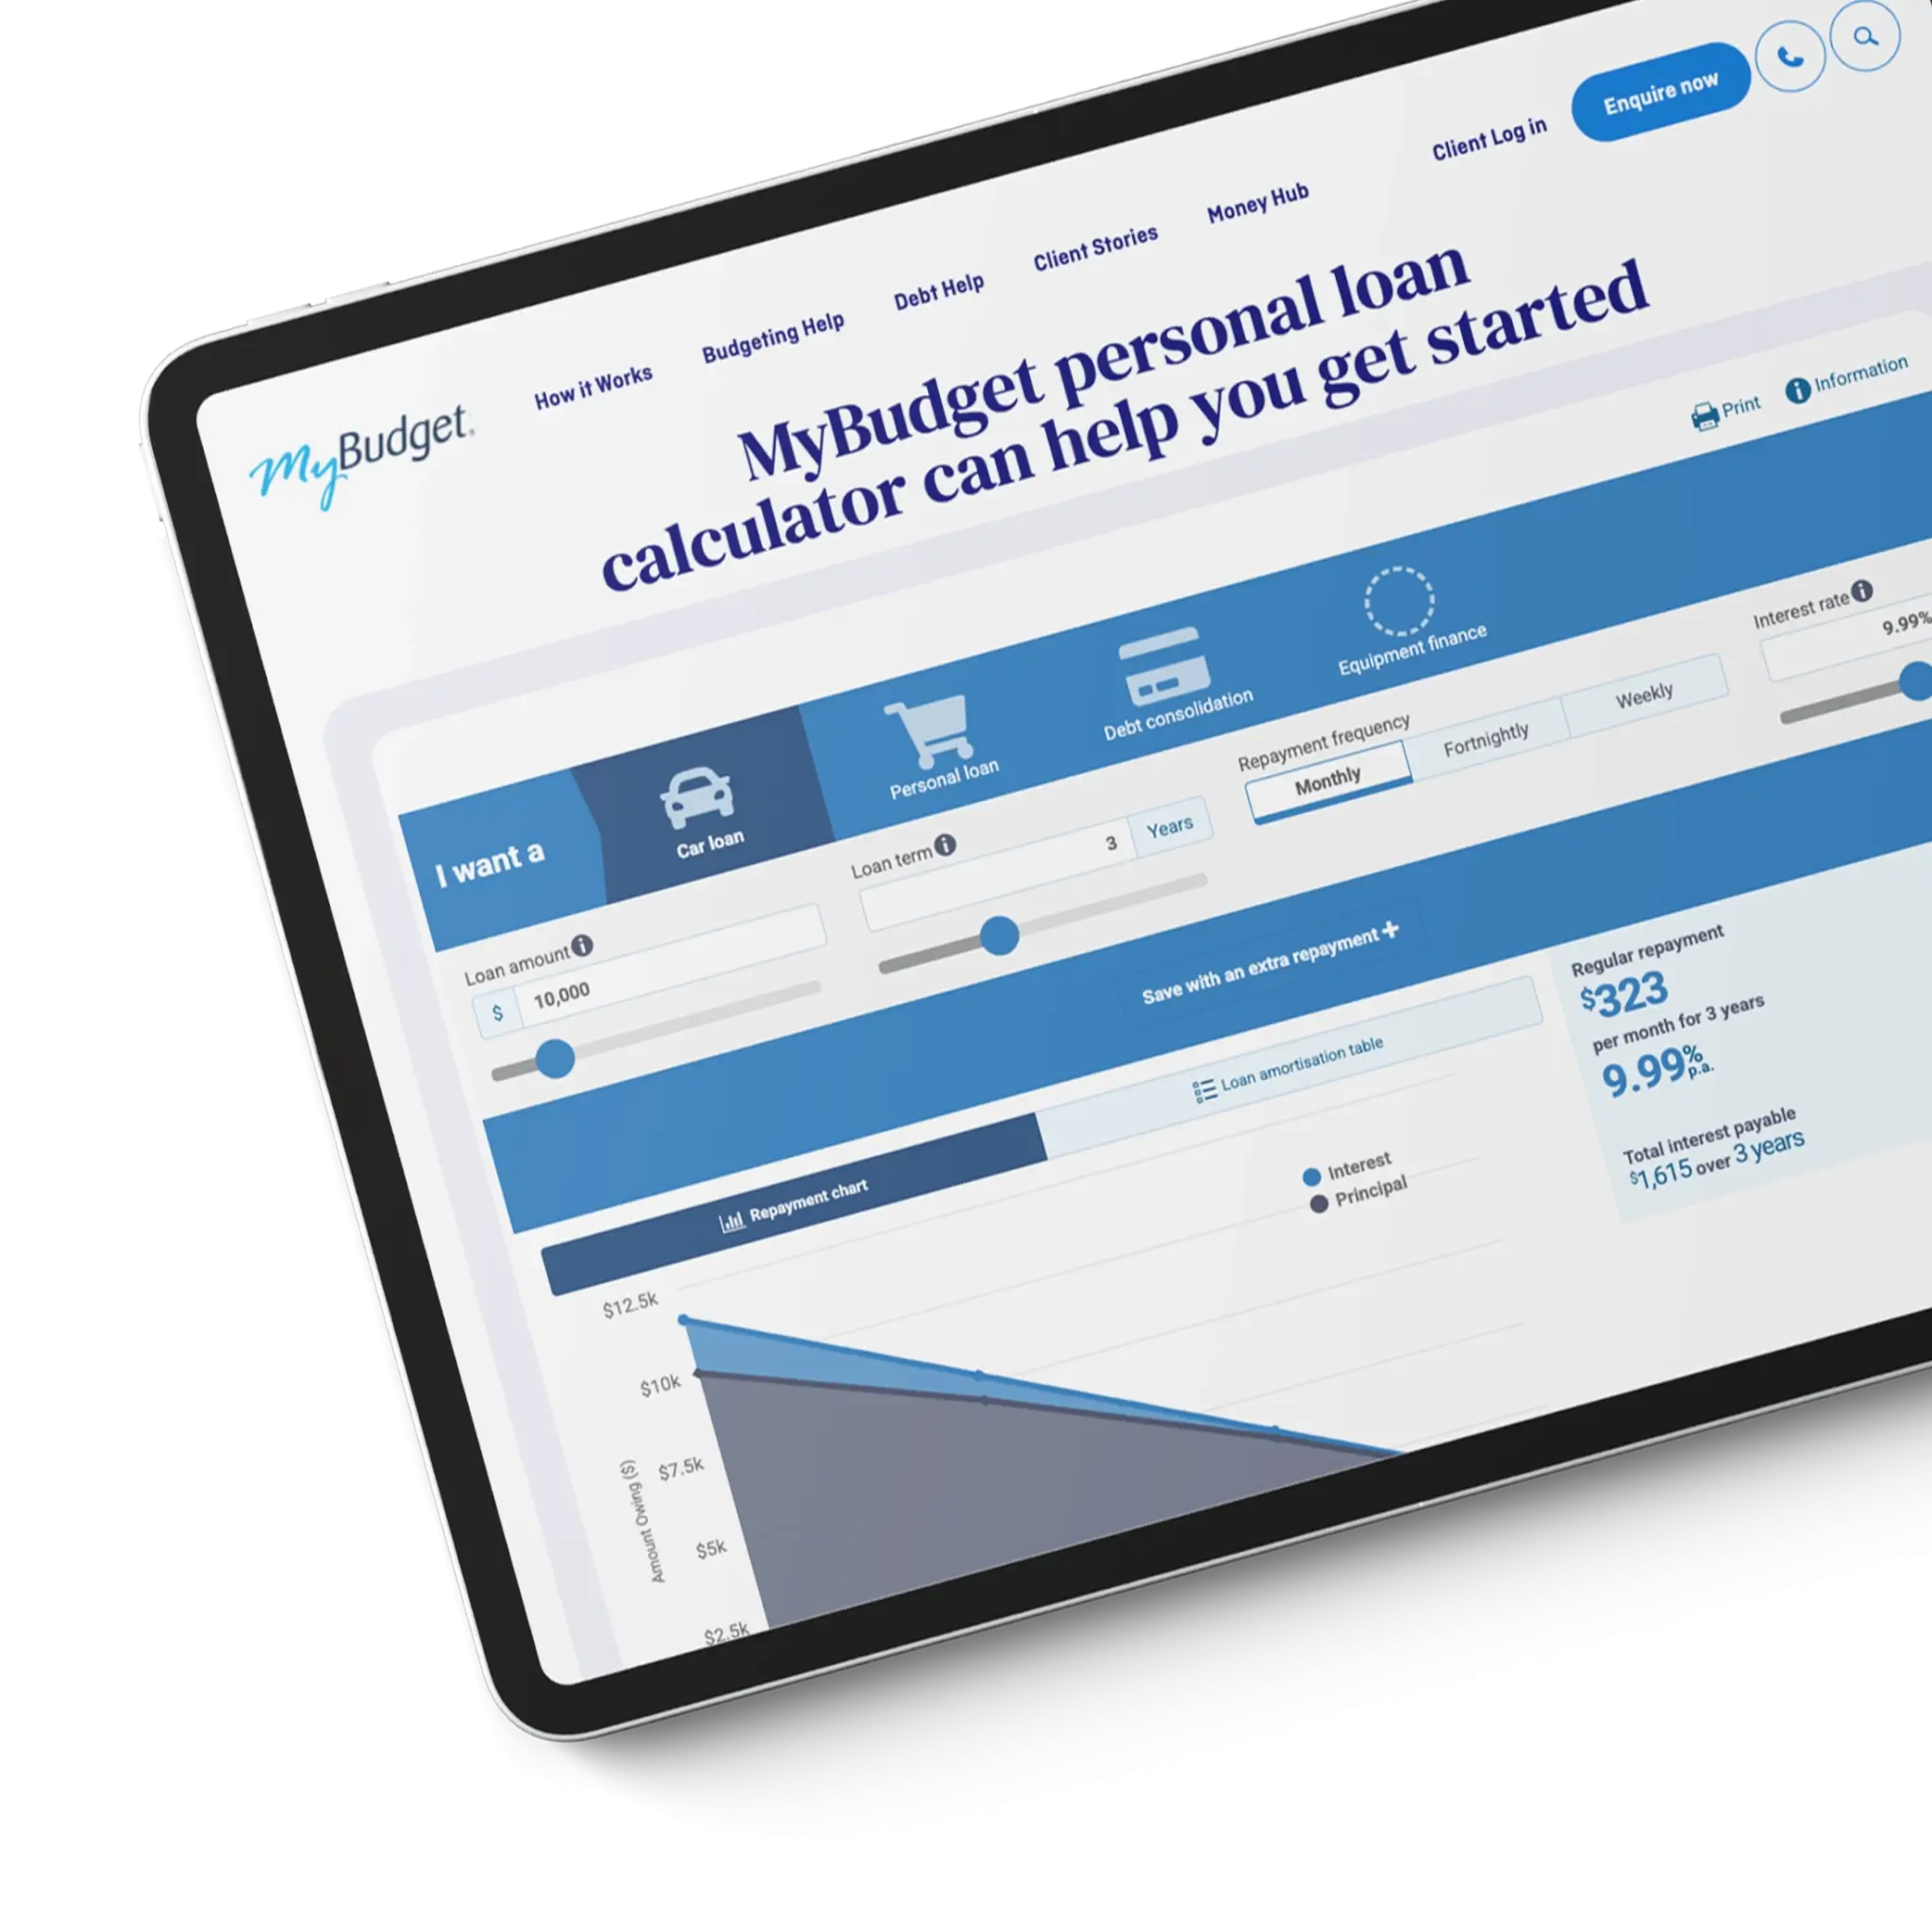
They’ve used MyBudget Loans when borrowing made sense for them
Kim and Bob had already used MyBudget Loans before consolidating their debts.
In 2021, Bob took out a $12,000 personal loan to buy a pre-loved car. Kim borrowed $10,000 in 2023 for a car and a trip to New Zealand to visit family.
Then came the $37,222.07 debt consolidation loan in April 2024.
Later that year, family circumstances changed again. Kim needed to travel to New Zealand to see her unwell father and used a $6,000 personal loan to make the trip.
In the past, we never did that. It was a struggle. But now it’s like, you want to go home, there’s money in the budget for it.
Bob | MyBudget Client
For Kim and Bob, borrowing has become something they plan for rather than something that simply fills a gap when money runs short.
Tammy Barton describes it this way:
Debt is part of life. It’s not something to be judged for or to feel shame about. The real question is whether your debt is supporting the life you are building or taking choices away from you.
Tammy Barton | MyBudget Founder & Director
Before Kim and Bob borrowed, their budget was checked to make sure the repayments were affordable.
Their early experience with debt came from trying to keep up when there wasn’t enough money to cover everything. More recent loans have been for specific needs, with the repayments worked into their budget before they borrowed.
What could debt consolidation change for you?
If you’re juggling several debts, combining them could make repayments easier to manage and may reduce how much you need to pay each month.
But your result will depend on your debts and the loan available to you.
Before consolidating, check the new interest rate, comparison rate, fees, loan term and total repayment amount. Then look at how the repayment fits into the rest of your monthly expenses.
You can learn more about debt consolidation or see how MyBudget Loans works.
For Kim and Bob, their April 2024 consolidation meant taking five debts totalling $37,222.07 and turning them into one repayment. The extra $875 in their monthly budget also gave them more room to think about what came next.
MyBudget Loans was an amazing experience. From start to finish we got the money in five days.
Kim | MyBudget Client
And after 16 years with MyBudget, they have plenty they’re looking forward to.
After travelling around Australia and returning to New Zealand to visit family on several occasions, they’re now planning a six-week trip to Vietnam and New Zealand for their 30th wedding anniversary. They’re also hoping to buy a house with their children in 2027.
Those plans are a long way from the days when Bob was working out whether his family might have to sleep in the car.
Now I can teach my kids, and even they see it in our lives every day that we’re able to spend money wisely.
Bob | MyBudget Client
Could debt consolidation make your repayments easier to manage?
MyBudget can look at your finances with you and help you understand your options. Your first appointment is free and comes with no obligation.
You can also explore MyBudget Loans debt consolidation options.
Debt Consolidation Loan FAQs
Can’t find what you’re looking for?
See more FAQs…
Their consolidation freed up $875 a month in their budget, or around $10,500 over 12 months. They also went from managing five separate debts to one repayment, making their debt easier to account for alongside their other household expenses.
A debt consolidation loan combines several existing debts into one new loan. You then make one regular repayment rather than paying several lenders separately. The interest rate, fees, loan term and total repayment cost should all be checked before deciding whether consolidation suits you.
No. Kim and Bob paid off around $28,000 across 12 accounts after joining MyBudget in 2010. Their debt consolidation loan came much later, in April 2024, when MyBudget Loans helped them combine five debts totalling $37,222.07 into one loan.
Yes. Later in 2024, Kim used a $6,000 personal loan to travel to New Zealand to see her unwell father. The couple had also used MyBudget Loans before the consolidation, including loans for cars and family travel.
This article has been prepared for information purposes only, and does not constitute personal financial advice. The information has been prepared without taking into account your personal objectives, financial situation or needs. Before acting on any information in this article you should consider the appropriateness of the information having regard to your objectives, financial situation and needs.